
Monthly Market Summary
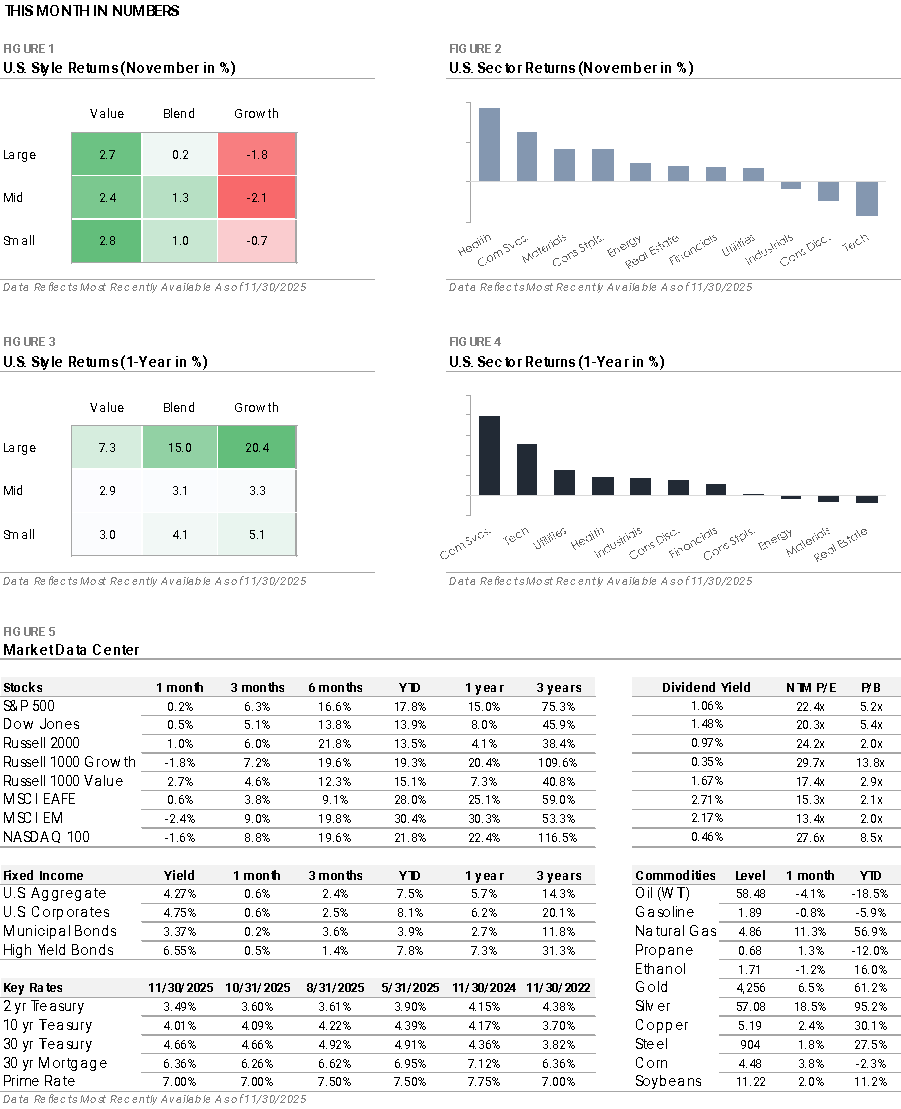
- The S&P 500 Index returned +0.2% in November, its seventh consecutive monthly gain. Large Cap Growth declined -1.8% as AI-related names came under pressure, while Large Cap Value rose +2.7%. The Russell 2000 and the Dow Jones Index both outperformed the S&P 500 as mega-cap tech stocks weighed down the index.
- Health Care led all S&P 500 sectors with a +9.3% return. Eight of the eleven S&P 500 sectors outperformed the index, while the Technology, Consumer Discretionary, and Industrials sectors each traded lower and underperformed the index.
- Bonds traded higher as Treasury yields ended the month lower despite intra-month volatility tied to uncertainty around a December rate cut. The U.S. Bond Aggregate gained +0.6%, increasing its year-to-date return to +7.5%. Investment-grade bonds matched the Aggregate’s +0.6% total return, edging out high-yield’s +0.5% gain.
- International stocks were mixed. Developed Markets gained +0.6%, modestly outperforming the S&P 500, while Emerging Markets fell -2.4%. Year-to-date, both regions are outperforming the S&P 500 by more than +10%.
The Market’s Tug-of-War with the Federal Reserve
The stock market was volatile in November as the Federal Reserve managed investor expectations for a December rate cut. The volatility started after the Fed’s late-October meeting, when Chair Powell said a December rate cut was “not a foregone conclusion”. Market-implied odds for a third consecutive rate cut fell from 98% in late October to around 40% in mid-November, as multiple Fed officials questioned the need for another rate cut. The uncertainty weighed on the stock market, with the S&P 500 trading lower and eventually bottoming on November 20th. Sentiment then shifted again late in the month as comments from influential Fed members, rising unemployment, and favorable inflation data pushed the odds of a December cut back above 80%.
The market’s reaction wasn’t just about a -0.25% rate cut, but rather what the Fed’s decision signaled about the future. A December cut would affirm the bullish narrative that the Fed was pulling off a “soft landing”, whereby the central bank proactively lowers interest rates to reduce the risk of recession. When the odds of a December cut initially fell, the market sold off as investors reassessed that optimistic outlook. Leaving rates unchanged would keep financial conditions tighter for longer, potentially slowing the economy and earnings growth. The late month rebound, fueled by rising expectations of a December cut, reflected increased clarity and confidence about the path ahead.
The AI Trade Moves to the Next Phase as Investors Become More Selective
Artificial intelligence remains a key market driver with 7 of the 10 largest S&P 500 companies, or nearly 30% of the index, tied to the AI industry. In November, there was a noticeable shift in investor sentiment toward AI stocks, moving from broad enthusiasm to increased scrutiny and selectivity. The month began with concerns over the expensive valuations of the Magnificent 7 tech giants, particularly those most reliant on the AI infrastructure buildout. Questions emerged about whether the massive capital spending on data centers and cloud infrastructure will translate into profits strong enough to justify the companies’ high valuations. This skepticism around AI’s economics led to a sell-off across the AI industry, with companies like Nvidia and Amazon down over -10% at times. Given the S&P 500’s extreme concentration in mega-cap technology stocks, the focused weakness was a major factor dragging down the index.
The AI investment cycle is maturing, with investors’ focus shifting from pure infrastructure spending to real-world application and monetization. Signs of AI fatigue have emerged as investors weigh the steep upfront costs against uncertain long-term economics and productivity gains. One example is Oracle, which has fallen nearly -40% since September due to concerns about its aggressive debt-funded data center expansion, highlights the growing cost anxiety. While AI remains a central theme in most 2026 market outlooks, investors are becoming more selective toward AI stocks, looking for tangible evidence of revenue growth and productivity improvements across the broader economy.
Important Disclosures
The financial advisors at Phases Financial Group operate as independent financial advisors for Addison Avenue Investment Services. Financial advisors offer securities through Raymond James Financial Services, Inc. Member FINRA/SIPC, and securities are not insured by credit union insurance, the NCUA or any other government agency, are not deposits or obligations of the credit union, are not guaranteed by the credit union, and are subject to risks, including the possible loss of principal. Phases Financial Group is not a registered broker/dealer and is independent of Raymond James Financial Services. Additionally, First Technology Federal Credit Union and Addison Avenue Investment Services are not registered broker/dealers and are independent of Raymond James Financial Services and Phases Financial Group. Investment advisory services are offered through Raymond James Financial Services Advisors, Inc.
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Style Box Performance: Russell 1000 Value, S&P 500, Russell 1000 Growth, Russell Midcap Value, Russell Midcap, Russell Midcap Growth, Russell 2000 Value, Russell 2000, Russell 2000 Growth.
Sector Performance: S&P 500 Consumer Discretionary, S&P 500 Consumer Staples, S&P 500 Energy, S&P 500 Financial, S&P 500 Health Care, S&P 500 Industrial, S&P 500 Materials, S&P 500 Technology, S&P 500 Communication Services, S&P 500 Utilities, S&P 500 Real Estate.
Market Data Center: S&P 500, DJ Industrial Average, Russell 2000, Russell 1000 Growth, Russell 1000 Value, MSCI EAFE, MSCI EM (Emerging Markets), NASDAQ100 Index, Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Broad Municipal, ICE BofA US High Yield.
Fixed Income Yields and Key Rates: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Treasury Bond, 10 Year US Treasury Bond, 30 Year US Treasury Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate,
Commodity Prices: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu),