
Monthly Market Summary
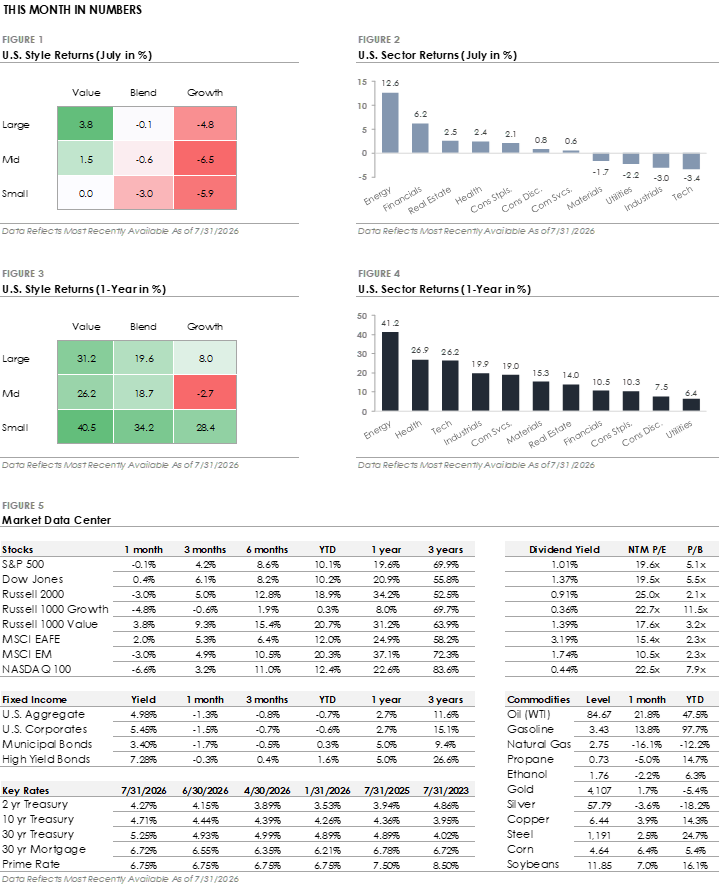
- The S&P 500 Index returned -0.1%. Energy led all S&P 500 sectors with a +12.6% return as geopolitical tensions caused oil to trade higher. Financials (+6.2%) was the second-best performing sector, followed by the defensive trio of Real Estate (+2.5%), Health Care (+2.4%), and Consumer Staples (+2.1%). Technology (-3.4%) underperformed as AI stocks gave back some of their gains from earlier in the year.
- Bonds traded lower as Treasury yields rose. The U.S. Bond Aggregate returned -1.3% as rising oil prices tied to the U.S.-Iran conflict reignited inflation concerns. Investment-grade corporates underperformed with a -1.5% total return, while high-yield corporates were relative outperformers with a -0.3% return.
- International stocks produced mixed returns during July. Developed markets gained +2.0% and outperformed the S&P 500, while emerging markets returned -3.0% and underperformed as the same U.S. tech selloff weighed on South Korean stocks.
Markets Turn Back to the Middle East as Tensions Resurface
The ceasefire from earlier this spring didn’t hold in July. Renewed conflict between the U.S. and Iran resurfaced the same headlines and concerns from earlier in the year, as uncertainty around the Strait of Hormuz once again raised the risk of reduced oil supply. Late-month headlines pointed to another round of de-escalation, but the conflict’s status remains fluid. The situation matters for the same reason it did the first time around: energy prices feed directly into inflation, and inflation impacts Federal Reserve policy. The Fed ultimately held interest rates steady for a fifth consecutive meeting in July, though a handful of officials pushed for a +0.25% rate hike given the renewed inflation risk.
This isn’t the first time this year that markets have moved through this cycle. There have been multiple mini cycles of conflict escalating, oil prices rising, and tensions easing, only for the pattern to repeat. The specific headlines and details shift from week to week, but markets have now absorbed the same shock more than once. The Fed’s split decision in late July reflects the lack of certainty. Officials are debating their next move but choosing to gather more information rather than react to headlines. Despite the headline volatility, the net impact on markets has been limited. The stock market rebounded from the March selloff, and the S&P 500 has returned nearly +10%.
AI Stocks Trade Lower as Investors Shift Focus from Growth to Discipline
Second quarter earnings season kicked off in July, with leading AI companies Alphabet, Microsoft, Meta, Apple, and Amazon all reporting. The group, which is investing heavily in data centers and other AI-related infrastructure, talked about their forecasts and spending plans. For the past two years, the conversation around AI centered on scale. Investors focused on how much companies were spending, how fast they were building, and how big the opportunity could become. This quarter, there was a noticeable shift toward profitability and return on investment.
In a shift from recent quarters, investors pushed back on the spending. Companies whose investments are translating into growth, like Microsoft’s cloud business, were rewarded, while others, whose spending has outpaced their cash flow or weighed on profit margins, saw their stocks trade lower. The market is no longer simply rewarding growth and big spending numbers. It’s asking whether the spending is profitable, or whether rising expenses are outpacing revenue growth. This is a natural and, in many ways, healthy form of discipline. Every major technological buildout eventually reaches a point where investors stop rewarding growth alone and start looking for it to be matched by results. July was the moment that question arrived for AI.
Semiconductor stocks, along with other parts of the AI trade, gave back some of their gains from earlier in the year as investors questioned the sustainability of current spending levels. Despite the semiconductor and AI selloff, the volatility was relatively contained. The equal-weight S&P 500, a proxy for the average S&P 500 stock, set a new all-time high late in the month, and seven of eleven S&P 500 sectors traded higher. Credit spreads, which measure the market’s concern about credit risk, expanded modestly but remain very tight by historical standards. Even after the pullback, semiconductor stocks are still up nearly +60% year-to-date. As for the companies doing the spending, they forecast even higher spending levels in the coming quarters.
The information herein was obtained from sources which MarketDesk Research LLC (MDR) believes to be reliable, but we do not guarantee its accuracy. Neither the information, nor any opinions expressed, constitute a solicitation of the purchase or sale of any securities or related instruments. MDR is not responsible for any losses incurred from any use of this information. The material was created by MarketDesk. Raymond James is not affiliated with MarketDesk.
Important Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Style Box Performance: Russell 1000 Value, S&P 500, Russell 1000 Growth, Russell Midcap Value, Russell Midcap, Russell Midcap Growth, Russell 2000 Value, Russell 2000, Russell 2000 Growth.
Sector Performance: S&P 500 Consumer Discretionary, S&P 500 Consumer Staples, S&P 500 Energy, S&P 500 Financial, S&P 500 Health Care, S&P 500 Industrial, S&P 500 Materials, S&P 500 Technology, S&P 500 Communication Services, S&P 500 Utilities, S&P 500 Real Estate.
Market Data Center: S&P 500, DJ Industrial Average, Russell 2000, Russell 1000 Growth, Russell 1000 Value, MSCI EAFE, MSCI EM (Emerging Markets), NASDAQ100 Index, Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Broad Municipal, ICE BofA US High Yield.
Fixed Income Yields and Key Rates: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Treasury Bond, 10 Year US Treasury Bond, 30 Year US Treasury Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate,
Commodity Prices: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).