
Monthly Market Summary
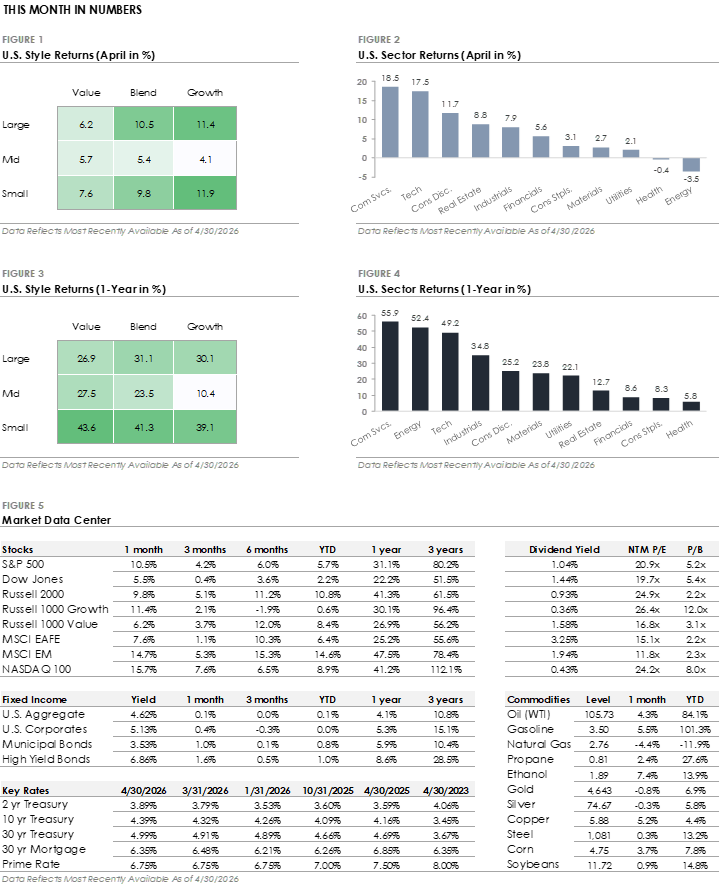
- The S&P 500 Index gained +10.5% in April, recovering its March decline and setting a new high. Communication Services led all S&P 500 sectors with a +18.5% return, followed by Technology (+17.5%) and Consumer Discretionary (+11.7%). Nine of eleven sectors traded higher as stocks recovered from the March selloff, but eight sectors underperformed the index as mega-cap stocks drove the bulk of the gains.
- Bonds traded lower as Treasury yields rose during the month. The U.S. Bond Aggregate returned +0.1% and underperformed corporate bonds as credit spreads tightened. High-yield’s +1.6% total return outpaced investment-grade’s +0.4% return as credit spread tightening benefited lower-quality bonds.
- International stocks underperformed the S&P 500 as U.S. Growth stocks led during the recovery. Emerging markets gained +14.7% and outperformed developed markets’ +7.6% return, with energy-importing regions like Europe and Japan impacted by the continued oil supply disruption.
Markets Rebound as Geopolitical Tensions Ease
Back-to-back ceasefires, first between the U.S. and Iran on April 7 and then between Israel and Lebanon on April 16, changed the market’s outlook. The agreements removed the worst-case scenario, and the reversal was immediate across markets. The S&P 500 erased all its March losses and went on to set a new all-time high by month-end. The Dow surged over 1,300 points the day the U.S.-Iran ceasefire took effect, its best day in a year. The Nasdaq Index gained nearly +16% during the month, driven by a historic semiconductor rally, and the Russell 2000 small-cap index gained +9.8% and set its own record. The recovery also reached beyond stocks. Credit spreads, which reflect how concerned the bond market is about corporate borrowers, reversed three months of widening in four weeks, and market uncertainty, as measured by the VIX Index, fell to pre-conflict levels.
The relief was broad and fast, but the underlying situation remains unsettled. The Strait of Hormuz, which carries roughly 20% of global oil supply, remains effectively closed, with only a few tankers crossing daily compared to hundreds before the conflict. Oil prices fell sharply on the ceasefire announcements, including the largest single-day decline since 2020, but have since risen back above $100 per barrel. Gasoline remained above $4 a gallon throughout April, and consumer confidence fell to its lowest reading in the University of Michigan survey’s 70-year history. The ceasefires reduced fears of further near-term escalation, and investors moved quickly to price that in. However, the oil supply disruption that’s become a part of the conflict has not been resolved.
AI Is Creating Winners and Losers Within the Tech Sector
The technology sector gained nearly +18% in April, but the gap between its strongest and weakest corners was wide. The divergence is being driven by artificial intelligence, which is simultaneously fueling demand in one part of the sector and raising fundamental questions about another. AI requires massive upfront investment to build and operate, including computer chips, data centers, power generation, and networking equipment. The companies that build the infrastructure are seeing a surge in demand as the physical backbone behind AI is constructed. At the same time, AI is advancing to the point where it can perform tasks that traditionally require human users interacting with software. AI agents, automated systems that can handle workflows like customer service, data entry, and internal reporting, are raising questions about the future of enterprise software.
The divergence could be seen in markets during April. Semiconductor stocks, which sell computer chips, rose more than +40% over 17 consecutive trading days, the longest uninterrupted winning streak for the group dating back to the early 1990s. Semiconductor funds absorbed $5.5 billion in new investment during the month, and earnings results from major chipmakers confirmed that infrastructure spending is translating into revenue growth. Enterprise software moved in the opposite direction. Several of the largest names in the industry have declined more than -30% this year, and the selling has even hit companies that beat earnings estimates and raised their forward guidance. The divergence comes as the market works through which business models AI will enhance and which it will disrupt. It’s a question likely to define not only the technology sector but also the broader market for some time.
The information herein was obtained from sources which MarketDesk Research LLC (MDR) believes to be reliable, but we do not guarantee its accuracy. Neither the information, nor any opinions expressed, constitute a solicitation of the purchase or sale of any securities or related instruments. MDR is not responsible for any losses incurred from any use of this information. The material was created by MarketDesk. Raymond James is not affiliated with MarketDesk.
Important Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Past performance does not guarantee future results. The performance information shown herein is based on total returns with dividends reinvested and does not reflect the deduction of advisory and/or other fees normally incurred in the management of a portfolio. Performance and fundamental data is based on the following instruments:
Style Box Performance: Russell 1000 Value, S&P 500, Russell 1000 Growth, Russell Midcap Value, Russell Midcap, Russell Midcap Growth, Russell 2000 Value, Russell 2000, Russell 2000 Growth.
Sector Performance: S&P 500 Consumer Discretionary, S&P 500 Consumer Staples, S&P 500 Energy, S&P 500 Financial, S&P 500 Health Care, S&P 500 Industrial, S&P 500 Materials, S&P 500 Technology, S&P 500 Communication Services, S&P 500 Utilities, S&P 500 Real Estate.
Market Data Center: S&P 500, DJ Industrial Average, Russell 2000, Russell 1000 Growth, Russell 1000 Value, MSCI EAFE, MSCI EM (Emerging Markets), NASDAQ100 Index, Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Broad Municipal, ICE BofA US High Yield.
Fixed Income Yields and Key Rates: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Treasury Bond, 10 Year US Treasury Bond, 30 Year US Treasury Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate,
Commodity Prices: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).